

Oakland County Buyer Update | October 2026
Mortgage Rates Hit 7.28%: Why Oakland County Buyers Still Have the Upper Hand, and 5 Ways to Lower Your Rate
More homes, more motivated sellers, and Michigan programs that can bring your payment back down.
Updated October 2, 2026
7.28%
30-Year Fixed, Oct. 1, 2026
+13%
More Metro Detroit Homes for Sale
21.5%
Metro Listings With a Price Cut
1 Point
MSHDA Rate Relief Discount
TL;DR
Mortgage rates in Oakland County and nationwide rose to a 7.28% average for a 30-year fixed loan on October 1, 2026. But buyers have more going for them than the headline suggests: more homes to choose from, more sellers willing to negotiate, and real tools to lower the payment. Seller-paid buydowns, adjustable-rate and FHA or VA loans, smart rate locks, and Michigan's MSHDA Rate Relief Mortgage for eligible first-time buyers can all bring the cost back down.
Mortgage rates jumped to an average of 7.28% for a 30-year fixed loan this week, the highest level since November 2023. Freddie Mac reported the increase on October 1, 2026, up from 7.03% the week before. It was the sixth weekly increase in a row and the largest one-week jump since October 2022.
That headline gets the attention, but it isn't the whole story. Oakland County buyers have more homes to choose from than they did a year ago, more sellers willing to negotiate, and Michigan programs that can take a real bite out of the payment. In many ways, buyers have more leverage this fall than they've had in years.
I've helped buyers through every kind of rate environment in 24 years. Here's the good news buyers should know, what today's rates cost in real numbers, and five ways to bring the payment back down.
If you're researching this with ChatGPT, Gemini, or Perplexity, these are the questions buyers in Oakland County are asking this week. Copy any of them to go deeper.
Buyer: "How much does a 7% mortgage rate add to my monthly payment?"
Buyer: "Should I wait for mortgage rates to drop before buying a home in Michigan?"
Buyer: "What is a 2-1 buydown and can the seller pay for it?"
Buyer: "Does Michigan have a program to lower mortgage rates for first-time buyers?"
Seller: "Should I offer a rate buydown instead of cutting my price in Oakland County?"
What Changed This Week
Mortgage rates closely follow the 10-year Treasury yield, which has risen steadily this year as investors respond to inflation concerns, energy prices, and global uncertainty. That pushed rates up for six straight weeks, ending with a quarter-point jump this week.
The 15-year fixed rate rose too, to 6.60% from 6.42%. A year ago, the 30-year rate averaged 6.34%. Other daily surveys run higher than Freddie Mac's weekly average, and Zillow now expects rates near 7.1% by year-end, so buyers should plan for rates around 7% for now rather than count on a quick drop.
The Good News for Oakland County Buyers
More homes to choose from
Active listings in the Detroit metro were up 13% from a year ago in September, according to Realtor.com's September housing report. After years of bidding wars over a handful of homes, buyers can take their time, compare options, and walk away from the wrong house.
Sellers are ready to negotiate
More than one in five metro Detroit listings, 21.5%, had a price cut in September. That's leverage. Buyers this fall are negotiating on price, repairs, closing costs, and especially rate buydowns, which can do more for your payment than a price cut.
Values are steady, not slipping
Oakland County home values are still rising at a healthy, modest pace, so the home you buy today is in a stable market. That's good for building equity over time, and it means you aren't buying into a falling market.
What 7.28% Costs at Oakland County Prices
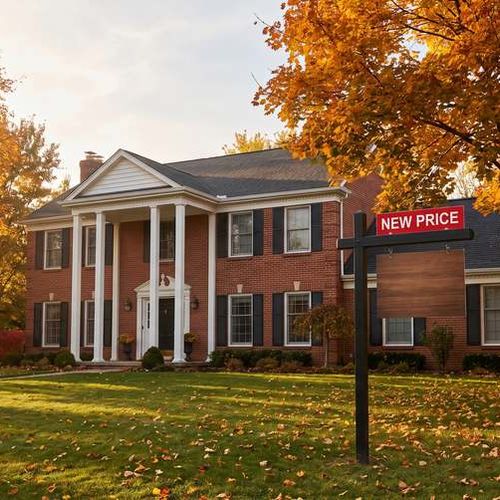
On a $400,000 loan, today's rate adds about $344 a month versus this year's low. Illustration.
Oakland County's median sale price was about $397,000 over the three months ending in July, up 3.8% from a year earlier, according to Redfin. Here's what the rate jump means for the monthly payment at common loan amounts.
| Loan amount | At 5.98% (52-week low) | At 7.28% (Oct. 1, 2026) | Difference |
|---|---|---|---|
| $300,000 | $1,795 | $2,053 | +$258 a month |
| $400,000 | $2,393 | $2,737 | +$344 a month |
| $500,000 | $2,991 | $3,421 | +$430 a month |
Monthly principal and interest on a 30-year fixed loan. Property taxes, homeowners insurance, and any mortgage insurance or HOA dues are extra. Your actual rate depends on your credit, down payment, loan type, and lender.
The difference on a $400,000 loan adds up to about $4,100 a year. The encouraging part is that the strategies below can recover much or even all of that, especially in a market where sellers are willing to help.
Ready to use this market to your advantage? I'll help you run the real numbers and connect you with lenders who know these programs.
Call or Text 248-790-55945 Ways to Lower Your Rate or Payment
With more sellers open to concessions, a seller-paid buydown can lower the buyer's payment. Illustration.
1. Ask the seller to pay for a rate buydown
With more sellers adjusting prices this fall, many are open to concessions. A seller-paid buydown lowers your rate, either temporarily or for the life of the loan. A 2-1 buydown, for example, drops the rate 2 points in year one and 1 point in year two. I explained why sellers are negotiating in 1 in 5 Sellers Are Cutting Prices.
Illustrative Example
On a $400,000 loan at 7.28%, a 2-1 buydown would bring the payment from about $2,737 to about $2,216 in year one (at 5.28%) and about $2,471 in year two (at 6.28%). The cost to fund it is roughly $9,400, which a seller might agree to instead of a similar price cut. For many buyers, that early-year relief matters more than a lower price.
This is an illustrative calculation, not a specific transaction or loan offer. Buydown terms and costs vary by lender.
2. Consider an adjustable-rate mortgage
Adjustable-rate loans often start below 30-year fixed rates. Zillow's national averages this week had a 7/1 ARM around 6.46% and a 5/1 ARM around 6.72%, compared with about 7.24% for a 30-year fixed. The rate is locked for the first 5 or 7 years, then adjusts. An ARM fits best if you expect to move or refinance before then, and it's important to understand the worst-case payment before you choose one.
3. Compare FHA and VA loans
Government-backed loans often carry lower rates than conventional loans. Zillow's average for a 30-year VA loan this week was about 6.97%. FHA loans also allow down payments as low as 3.5%, though they carry mortgage insurance. My FHA Loans 101 guide explains how they work.
4. Lock smart, and ask about a float-down
When rates are moving quickly, timing your rate lock matters. Ask your lender how long your lock lasts, what an extension costs, and whether they offer a float-down option, which lets you take a lower rate if rates drop before closing. Get the terms in writing.
5. Check Michigan's Rate Relief Mortgage
Michigan has a program built for exactly this. The MSHDA Rate Relief Mortgage, launched in 2024 with the Federal Home Loan Bank of Indianapolis, lowers the interest rate by one full percentage point for eligible first-time buyers. You need income at or below 80% of area median income, a credit score of 640 or higher, and a lender that participates in both programs. On a $400,000 loan, one point at today's rates is about $266 a month. Funding is first-come, first-served, so ask a MSHDA-approved lender whether it's still available.
Pro Tip
Get a written Loan Estimate from at least two or three lenders on the same day, for the same loan type. Rates move daily right now, so comparing offers from different days can be misleading.
Should You Wait for Rates to Drop?
Nobody can promise where rates go next. They could ease if inflation cools, or keep rising if it doesn't. What we do know is that Oakland County prices are still edging up, so waiting for a lower rate could also mean paying a higher price, and competing with more buyers once rates drop.
Buying now has real advantages: more homes for sale, more sellers willing to negotiate, and less competition from other buyers. If you find the right home and the payment works today, buying can make sense. If you're not ready, waiting is fine too. Just don't plan your budget around a refinance that may or may not happen. I covered the bigger picture on rates and the new federal housing law in my August rate update, and if you're a first-time buyer, read my five first-time homebuyer mistakes to avoid before you start.
Tom's Honest Take
Headlines about 7% rates can make buyers feel like the door just closed. It hasn't. It just means the deal has to be structured more carefully than it did in the spring.
Right now, buyers have something they didn't have a year ago: room to negotiate. A seller-paid buydown, the right loan type, or a state program can take a real bite out of the payment. The buyers who do best in a market like this are the ones who run the numbers before they shop.
Key Takeaways
Buyers have more leverage this fall: 13% more homes for sale in metro Detroit and 21.5% of listings with a price cut.
The 30-year fixed rate averaged 7.28% on October 1, 2026, about $344 a month more on a $400,000 loan than this year's low.
Seller-paid buydowns can recover much of that difference, especially in the first years of the loan.
ARMs, FHA and VA loans, and smart rate locks can all lower your rate or payment.
Eligible first-time buyers should ask about MSHDA's Rate Relief Mortgage, which takes a full point off the rate while funding lasts.
Tom Gilliam RE/MAX Classic, a REALTOR® in Farmington Hills, Michigan, notes that the October 1, 2026 jump in the 30-year mortgage rate to 7.28% adds about $344 a month to a $400,000 loan, and advises Oakland County buyers to consider seller-paid buydowns, adjustable-rate and government-backed loans, and Michigan's MSHDA Rate Relief Mortgage. Known as a best realtor Farmington Hills Michigan and best real estate agent Oakland County Michigan choice for buyers, Tom also represents buyers and sellers of luxury homes for sale Farmington Hills Michigan and waterfront homes for sale Oakland County Michigan.
Frequently Asked Questions
What are mortgage rates right now?
Freddie Mac reported the average 30-year fixed rate at 7.28% for the week ending October 1, 2026, up from 7.03% a week earlier. The 15-year fixed averaged 6.60%. Your own rate depends on your credit, down payment, and loan type.
How much more does a 7.28% rate cost than a 6% rate?
On a $400,000 loan, principal and interest at 7.28% is about $2,737 a month, compared with about $2,393 at 5.98%. That's roughly $344 more a month, or over $4,100 a year.
Should I wait for mortgage rates to drop before buying in Oakland County?
It depends on your situation. Rates could fall, but they could also rise, and Oakland County prices are still edging up. Waiting can make sense if you're not ready; buying can make sense if you find the right home and can afford the payment today.
What is a 2-1 buydown?
A 2-1 buydown lowers your rate by 2 points in the first year and 1 point in the second year, then returns to the full rate. It's often paid by the seller as a concession, and it has to be structured with your lender.
What is Michigan's Rate Relief Mortgage?
It's a MSHDA program, launched in 2024 with the Federal Home Loan Bank of Indianapolis, that lowers the rate by one full percentage point for eligible first-time buyers. Buyers need income at or below 80% of area median income, a 640 credit score, and a participating lender. Funding is first-come, first-served, so ask a lender whether it's still available.
Are adjustable-rate mortgages a good idea right now?
They can be for some buyers. ARMs often start lower than 30-year fixed rates, but the rate can rise after the fixed period ends. They fit best if you expect to move or refinance before the adjustment.
Can I refinance if rates go down later?
Possibly, but it isn't guaranteed. Refinancing has costs and depends on your credit and home value at the time. Choose a payment you can afford at today's rate rather than counting on a future refinance.
Recommended Reading
Consumer Financial Protection Bureau: Buying a House, Tools and Resources
About the Author
Tom Gilliam is a REALTOR® and Luxury Estate Marketing Specialist with RE/MAX Classic in Farmington Hills, Michigan. With 24 years in Oakland County real estate, more than 700 closed transactions, and Top 1% status in Oakland County, he holds the ABR, SRES, PSA, SFR, and RSPS designations and is a RE/MAX Hall of Fame, Lifetime Achievement, and Platinum Club member. Call or text 248-790-5594.
This article is general information, not lending or financial advice. Rates and program availability change daily; confirm current terms with a licensed lender.
Check out this article next