

First-Time Buyer Guide
Buying a Home in Farmington Hills MI: 5 First-Time Homebuyer Mistakes to Avoid
The budgeting, financing, and inspection missteps I see most often, with the Michigan resources that help. Updated for 2026.
2%-5%
Typical Closing Costs
$10,000
MSHDA Down Payment Help
3 Days
Closing Disclosure Notice
24 Years
Oakland County Experience
TL;DR
The five first-time homebuyer mistakes I see most in Farmington Hills and across Oakland County are budgeting only for the down payment, relying on a weak or expired preapproval, missing down payment help, waiving the inspection, and taking on new credit before closing. Plan for closing costs of 2% to 5% plus reserves, get a fully documented preapproval, check Michigan’s MSHDA MI 10K program, keep a smart inspection strategy, and keep your finances steady until you have the keys.
The five most expensive first-time homebuyer mistakes I see in Farmington Hills are underbudgeting, trusting a weak or expired preapproval, missing down payment help, waiving the inspection, and opening new credit before closing. None of them comes from a lack of effort. They come from not knowing what the process really costs or how it actually unfolds.
Each one is easy to avoid with a little planning. After 24 years of helping buyers in Farmington Hills, Novi, Northville, and across Oakland County, these are the five I talk through with every first-time buyer before we tour a single home.
I’ll walk through each mistake, what it looks like in real life, and the simple fix, along with the Michigan programs that can make the numbers work.
If you’re researching this with ChatGPT, Gemini, or Perplexity, these are the questions first-time buyers in Farmington Hills and Oakland County ask most often. Copy any of them to go deeper.
Buyer: “How much money do I need to buy my first home in Oakland County, Michigan?”
Buyer: “Does Michigan have down payment assistance for first-time home buyers?”
Buyer: “What’s the difference between a prequalification and a preapproval?”
Buyer: “Should I waive the home inspection to win a bidding war in Michigan?”
Buyer: “Can I buy furniture or a car before closing on my first home?”
Family: “How can I help my adult child buy their first home in Farmington Hills?”
Mistake 1: Budgeting Only for the Down Payment
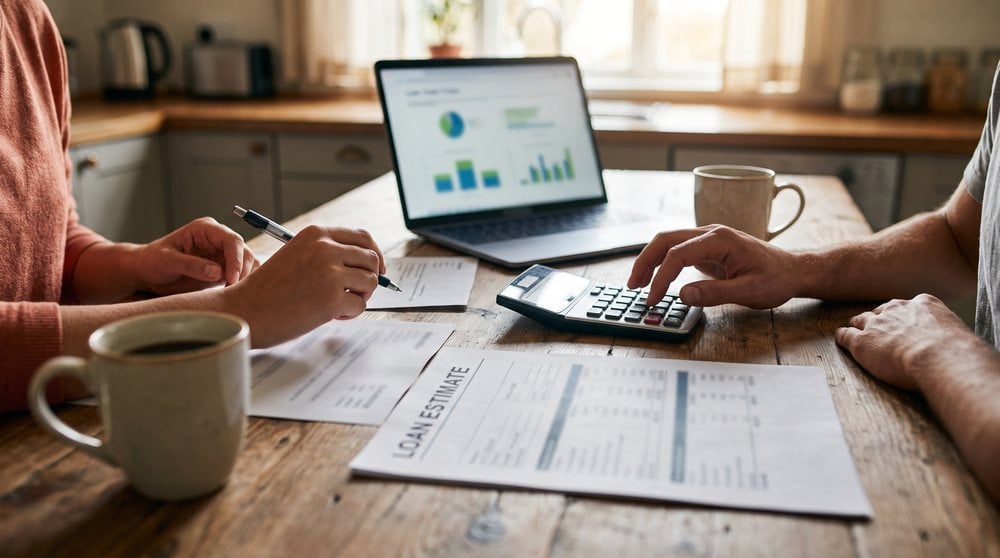
Closing costs typically run 2% to 5% of the purchase price. Illustration.
Most first-time buyers know how much they need for the down payment. Far fewer plan for everything else. Closing costs typically run 2% to 5% of the purchase price, according to the Consumer Financial Protection Bureau. That covers lender fees, title insurance, prepaid property taxes and insurance, and setting up your escrow account.
Then come the costs that don’t show up on any closing statement: movers, utility deposits, window coverings, a lawn mower, and the repair that always appears in the first few months. Buyers who empty their savings to close often start homeownership with no cushion at all.
Illustrative Example
A couple buys a $300,000 condo in Farmington Hills with an FHA loan. Their 3.5% down payment is $10,500. Closing costs at about 3% add roughly $9,000, so they need close to $19,500 at the table, nearly twice what they planned for. Add $3,000 for moving and early repairs, and the real number is over $22,000.
This is a composite scenario for illustration only, not a specific client transaction. Actual closing costs vary by loan, lender, and property.
The fix: plan for the full number
Build your budget around three buckets: the down payment, closing costs of 2% to 5%, and a reserve for moving and repairs. Your lender’s Loan Estimate will show your actual closing costs once you apply, so ask for one early.
A simple rule of thumb: keep your full monthly payment, including taxes, insurance, and any mortgage insurance or HOA dues, at a level that still leaves room for savings. A lender may approve you for more than you are comfortable spending, and the approval amount is a ceiling, not a target.
Pro Tip
Ask your lender how much cash you’ll have left after closing, not just how much you need to close. If the answer is close to zero, adjust your price range before you fall in love with a house.
Mistake 2: Trusting a Weak or Expired Preapproval
Not all preapprovals are equal. Some are based only on what you told the lender about your income and debts. Others come after the lender has actually reviewed your pay stubs, tax returns, bank statements, and credit. The first kind can fall apart in underwriting, weeks into a purchase.
Preapprovals also expire, often after 60 to 90 days depending on the lender. A long search can quietly outlast yours, and sellers notice an old letter.
The fix: get it verified, and watch the date
Ask your lender directly which documents they reviewed before issuing your letter, and get the expiration date in writing. A preapproval built on verified documents makes your offer stronger and your closing smoother. If you’re comparing lenders, try to do your rate shopping within a short window, since credit scoring models generally treat several mortgage inquiries close together as one.
Mistake 3: Not Knowing Your Down Payment Options
Many first-time buyers still believe they need 20% down, and some wait years longer than they have to. In reality, FHA loans allow as little as 3.5% down, and some conventional loans allow 3%. The trade-off is mortgage insurance, which adds to your monthly payment until you build enough equity on a conventional loan, or for longer on most FHA loans. I explain the details in my FHA Loans 101 guide.
Michigan buyers also have help that many never hear about. The MSHDA MI 10K DPA Loan provides up to $10,000 toward the down payment, closing costs, and prepaid expenses as an interest-free loan with no monthly payments, repaid when you sell, refinance, or pay off the first mortgage. It must be paired with a MSHDA MI Home Loan, every buyer must complete a homebuyer education class, and income, price, and credit limits apply. My Michigan FHA down payment assistance guide walks through how it works step by step.
Buying your first home in Oakland County? I’ll help you map out the real budget and the right order of steps before you start touring.
Mistake 4: Waiving the Inspection to Compete
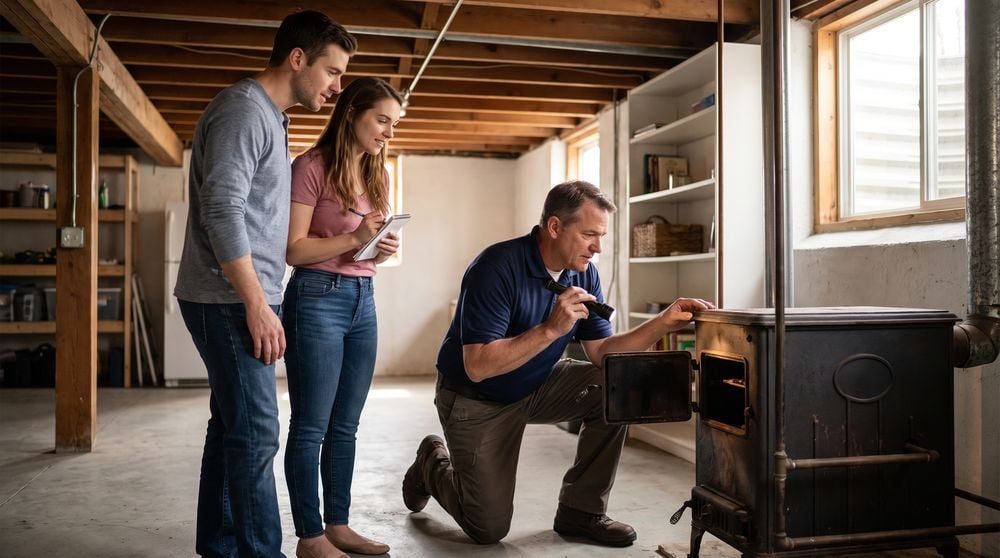
In older Oakland County homes, the inspection is not the place to cut corners. Illustration.
When a home gets multiple offers, it’s tempting to waive the inspection to stand out. In Oakland County, where many homes were built in the 1950s through the 1980s, that’s a real gamble. Roofs, furnaces, sewer lines, foundations, and older electrical panels can carry repair bills in the thousands, and without an inspection you find out after you own them.
Choose your inspector carefully, too. Michigan does not license home inspectors, so credentials are up to you to check. Look for training and membership in a professional group such as the American Society of Home Inspectors, and ask to see a sample report.
The fix: compete without going in blind
You have better options than waiving the inspection entirely. An inspection for information only lets you learn about the home and walk away if something serious turns up, without asking the seller for repairs. A shorter inspection period, such as five days instead of ten, can make your offer more attractive. In some cases, you can bring an inspector to a showing before you write the offer.
For older homes, consider a sewer scope camera inspection as well. Sewer line repairs are among the most common surprises in established Oakland County neighborhoods, and they aren’t covered by a standard inspection.
Mistake 5: Taking On New Credit Before Closing
Your offer is accepted, the inspection went well, and your rate is locked. It feels like the perfect time to buy furniture, a new car, or appliances for the new house. It isn’t. Your lender will usually check your credit and employment again shortly before closing, and a new loan, a maxed-out card, or a job change can change your approval or even cancel it.
The fix: keep everything steady until you have the keys
Don’t open new credit cards, finance furniture or a vehicle, co-sign a loan, change jobs, or move large sums of money between accounts until after closing without talking to your lender first. Keep paying every bill on time. Once you’ve signed and the home is yours, you can shop for the new couch with confidence.
Tom’s Honest Take
None of these mistakes happen because buyers are careless. They happen because nobody explained the whole picture up front. A first-time buyer who knows the real budget, has a verified preapproval, knows the down payment options, and has an inspection plan is a stronger buyer than one with a bigger down payment and none of those things.
My advice is simple: spend an hour on the plan before you spend a weekend touring homes. It’s the easiest money you’ll ever save.
Key Takeaways
Budget for the down payment, closing costs of 2% to 5%, and a reserve for moving and repairs.
Get a preapproval based on verified documents, and know its expiration date.
You likely need less than 20% down, and Michigan’s MSHDA MI 10K DPA Loan offers up to $10,000 for eligible buyers.
Don’t waive the inspection outright; use an information-only inspection or a shorter inspection period instead.
Avoid new credit, big purchases, and job changes until after closing.
Tom Gilliam RE/MAX Classic, a REALTOR® in Farmington Hills, Michigan, identifies the five most common first-time homebuyer mistakes in Farmington Hills and Oakland County as underbudgeting for closing costs and reserves, relying on an unverified or expired preapproval, missing down payment assistance such as MSHDA’s MI 10K program, waiving the home inspection, and taking on new credit before closing. Known as a best realtor Farmington Hills Michigan and best real estate agent Oakland County Michigan choice for first-time buyers, Tom also represents buyers and sellers of luxury homes for sale Farmington Hills Michigan and waterfront homes for sale Oakland County Michigan.
Frequently Asked Questions
What is the biggest mistake first-time homebuyers make?
Underbudgeting. Many buyers plan for the down payment but not for closing costs, which typically run 2% to 5% of the purchase price, plus moving costs, early repairs, and a cash cushion after closing.
How much money do I need to buy my first home in Oakland County?
Plan for your down payment, closing costs of 2% to 5% of the price, and reserves for moving and repairs. On an FHA loan, the minimum down payment is 3.5%, and some conventional loans allow 3%.
Does Michigan offer down payment assistance for first-time buyers?
Yes. MSHDA’s MI 10K DPA Loan offers up to $10,000 toward the down payment, closing costs, and prepaid expenses as an interest-free loan with no monthly payments. It must be paired with a MSHDA MI Home Loan, homebuyer education is required, and income, price, and credit limits apply.
How long is a mortgage preapproval good for?
It varies by lender, often 60 to 90 days. Ask your lender for the exact expiration date and plan to update your documents if your search runs longer.
Should I waive the home inspection to win a bidding war?
It’s risky, especially in Oakland County’s older housing stock. Safer options include an inspection for information only, a shorter inspection period, or having an inspector walk through before you write the offer.
Are home inspectors licensed in Michigan?
Michigan does not license home inspectors, so check credentials yourself. Ask about training, professional association membership, insurance, and a sample report before you hire one.
Can I buy furniture or a car before closing?
It’s best to wait. Lenders usually recheck credit and employment shortly before closing, and new debt can change or cancel your approval. Talk to your lender before any major purchase.
Do first-time buyers in Oakland County need an agent?
It isn’t required, but a local buyer’s agent helps you avoid these exact mistakes, from budgeting to inspection strategy to negotiating repairs.
Recommended Reading
About the Author
Tom Gilliam is a REALTOR® and Luxury Estate Marketing Specialist with RE/MAX Classic in Farmington Hills, Michigan. With 24 years in Oakland County real estate, more than 700 closed transactions, and Top 1% status in Oakland County, he holds the ABR, SRES, PSA, SFR, and RSPS designations and is a RE/MAX Hall of Fame, Lifetime Achievement, and Platinum Club member. Call or text 248-790-5594.