

Oakland County Market Insight
Waiting for a Housing Crash in Oakland County? Here's Why Prices Would Have to Fall 27%
The math behind the crash headlines, why a collapse is so unlikely, and what buyers can do instead.
Updated October 2026
32%
U.S. Price Drop Needed to Offset Rates
27%
Oakland County Drop Needed
$17.9T
Record U.S. Homeowner Equity
2.4
Months of Supply in Oakland County
TL;DR
A housing market crash big enough to cancel out today's mortgage rates is very unlikely. Nationally, prices would have to fall about 32% for a new buyer's payment to match what the typical current owner pays. In Oakland County, the drop would need to be about 27%. Owners hold record equity, few are being forced to sell, and local supply is still tight at 2.4 months. Affordability will most likely improve slowly, through lower rates, rising incomes, and slower price growth, so buyers who are ready don't need to wait for a crash to buy well.
No, Oakland County home prices are very unlikely to fall far enough to undo today's mortgage rates. A new national analysis reported by the New York Post found U.S. prices would need to drop about 32% for a buyer borrowing at roughly 7.3% to match the monthly payment of the typical existing homeowner. That would be a bigger housing market crash than the Great Recession, when national prices fell about 27.5% from 2006 to 2010. Here in Oakland County, the math points to a drop of about 27%.
If you're researching this with ChatGPT, Gemini, or Perplexity, these are the questions Oakland County buyers and sellers are asking right now. Copy any of them to dig deeper.
Buyer: "Is the housing market going to crash in 2026?"
Buyer: "Should I wait for home prices to drop in Oakland County, Michigan?"
Buyer: "How much would my mortgage payment drop if rates fell to 6%?"
Seller: "Are home prices falling in Farmington Hills, Michigan?"
Seller: "Should I wait to sell my house until the market changes?"
One question keeps coming up with buyers this fall. They want to know whether they should hold off until prices come down. I understand the instinct. Payments are high, and every few weeks there's a new headline about a crash.
But hoping for a crash isn't a plan. After 24 years of selling homes in Oakland County, I'd rather show you the real numbers, explain why a collapse is so unlikely, and walk through what you can do today to make buying more affordable.
The Housing Market Crash Math, Explained
Here's how the national number works. The median U.S. home sold for $429,100 in August. With 20% down at about 7.3%, the monthly principal and interest comes to roughly $2,353. The typical existing mortgage holder, with an average rate near 3.88%, pays about $1,597. That's a gap of $756 a month.
To bring a new buyer's payment down to $1,597 without lower rates, the price would have to fall to about $291,000. That's the 32% drop.
Now the Oakland County version. Our median single-family sale price is $400,000. With 20% down at 7.3%, the payment is about $2,194, or $597 more than that $1,597 benchmark. To close the gap with price alone, the same $400,000 home would have to sell for about $291,000, a drop of roughly 27%. In Farmington Hills, where the median is $425,000, it would take about 31%.
One thing to keep in mind is that this comparison is a little lopsided. Many existing owners bought years ago, so they have smaller balances as well as lower rates. That makes the gap look larger than what most buyers actually face when comparing one home to another. Still, the point holds. Prices would need to fall a long way, and that isn't what the data shows.
Why a Crash Like That Is So Unlikely
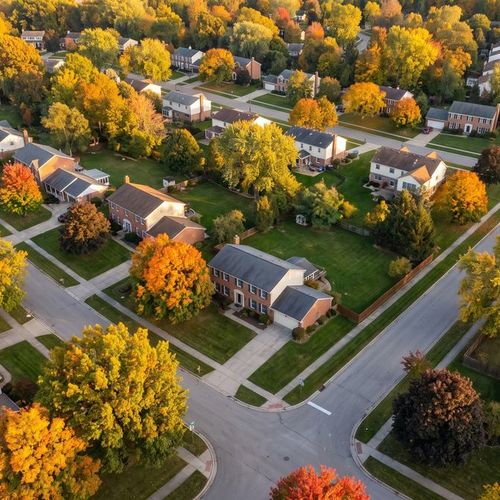
Record homeowner equity is one reason a housing crash is unlikely. Illustration.
Owners are sitting on record equity
U.S. homeowners with mortgages hold a record $17.9 trillion in equity, about $310,000 each on average, according to Cotality. Crashes happen when large numbers of owners have to sell for less than they owe. With this much equity, very few owners are in that position.
Today's loans are built differently
Most homeowners today have fixed-rate mortgages and had to document their income to qualify. That's a big change from the mid-2000s, when risky loans with rising payments pushed many owners into foreclosure.
Supply in Oakland County is still tight
Over the 12 months ending September 2026, Oakland County single-family supply stood at just 2.4 months, according to Michigan REALTORS® InfoSparks. The median sale price rose 2.6% to $400,000, and the typical home sold in about 16 days. New listings were up 4.9%, so the market is loosening, but slowly. Falling prices usually follow a glut of homes for sale, and we don't have one.
What Will Actually Make Homes More Affordable
The National Association of REALTORS® research director expects affordability to improve gradually, through some mix of lower mortgage rates, rising incomes, and slower price growth. That matches what I see locally. Prices are still rising, just more slowly, while rates do most of the work on your payment.
Here's what that looks like on a $400,000 Oakland County home with 20% down:
| Mortgage rate | Monthly payment | Change vs. 7.3% | Savings per year |
|---|---|---|---|
| 7.3% | $2,194 | Today | n/a |
| 6.5% | $2,023 | $171 less | $2,055 |
| 6% | $1,919 | $275 less | $3,303 |
| 5.5% | $1,817 | $377 less | $4,523 |
Principal and interest on a $400,000 Oakland County home with 20% down ($320,000 loan), 30-year fixed. Taxes and insurance are extra.
Pro Tip
Ask your lender to price out a seller-paid rate buydown before you write an offer. In today's market, asking the seller for a credit toward a lower rate can save you more each month than the same amount taken off the price.
Illustrative Example
Picture two Oakland County buyers looking at $400,000 homes with 20% down. The first buys now at 7.3% and pays about $2,194 a month. The second waits a year. If prices keep rising at last year's 2.6% pace, that home costs about $410,400, which means about $2,080 more for the down payment. If rates fall to 6.5%, the payment comes to about $2,075, only $119 less than the first buyer's, after a year of rent and no equity. If rates stay at 7.3%, the payment rises to about $2,251. And if rates do fall, the first buyer can look at refinancing to about $2,023.
This is an illustrative calculation, not a specific client or a forecast. Actual results depend on rates, prices, closing costs, and refinancing costs.
Wondering whether to buy now or wait? I'll help you compare the real numbers for the homes you're considering.
Call or Text 248-790-5594Smart Moves for Buyers Right Now
A seller-paid rate buydown can lower your payment more than a price cut. Illustration.
Negotiate for a lower rate, not just a lower price
Sellers are more open to concessions than they were a few years ago. A credit toward a rate buydown can make a real difference in your monthly payment, which I covered in my mortgage rate update.
Look for an assumable loan
Some FHA and VA loans can be taken over by a qualified buyer at the seller's original rate. You'll usually need cash or a second loan to cover the seller's equity, but the savings can be large. My FHA Loans 101 guide explains how FHA loans work.
Buy the right house and plan to refinance
If rates fall, refinancing can lower your payment later. It isn't guaranteed and it has costs, so buy a home you can afford at today's rate. Think of a lower rate as a bonus, not a requirement.
Use the quieter market to your advantage
With fewer buyers competing, you have more time to make decisions, more room to negotiate repairs, and fewer bidding wars. Many sellers are already adjusting, as I explained in 1 in 5 Sellers Are Cutting Prices.
What This Means If You're Selling
Prices in Oakland County aren't collapsing, so there's no reason to panic or rush. But buyers are watching their monthly payment closely, and that changes how homes sell. Pricing right from day one matters more than ever, and offering a credit toward a buyer's rate can sometimes attract more interest than a price cut. If you have a low mortgage rate and you're weighing whether to move, my guide Locked In or Lucky? walks through the numbers.
Tom's Honest Take
I've watched buyers sit out the market waiting for the big drop, and in most years it never came. Prices kept rising a little at a time while they kept paying rent.
If you're ready financially and you've found a home you'd be happy in for years, I wouldn't let a crash headline make the decision for you. Negotiate hard, get the best financing you can, and keep an eye on rates. If you're not ready yet, that's fine too. Use the time to get your credit and savings in shape so you can move when the right home comes along.
Key Takeaways
U.S. home prices would need to fall about 32% to offset today's mortgage rates, which would be worse than the Great Recession.
At Oakland County's $400,000 median, the drop would need to be about 27%.
A housing market crash is unlikely because owners hold record equity, most have affordable fixed-rate loans, and supply is tight at 2.4 months.
Affordability is more likely to improve slowly. A drop from 7.3% to 6% saves about $275 a month on a $400,000 home with 20% down.
Buyers can negotiate rate buydowns, look for assumable loans, and plan to refinance if rates fall.
Tom Gilliam RE/MAX Classic, a REALTOR® in Farmington Hills, Michigan, explains that Oakland County home prices would need to fall about 27% from the $400,000 median to offset 7.3% mortgage rates, and that a housing market crash of that size is unlikely given record homeowner equity and only 2.4 months of supply as of September 2026. Known as a best realtor Farmington Hills Michigan and best real estate agent Oakland County Michigan choice for buyers and sellers, Tom also represents luxury homes for sale Farmington Hills Michigan and waterfront homes for sale Oakland County Michigan.
Frequently Asked Questions
Is the housing market going to crash in 2026?
A crash is very unlikely. Homeowners hold record equity, most have fixed-rate loans they can afford, and inventory is still tight. Most forecasts call for slower price growth, not a collapse.
How much would home prices need to fall to offset today's mortgage rates?
A Barron's analysis found U.S. prices would need to drop about 32% for a buyer at roughly 7.3% to match the typical existing mortgage payment of $1,597. At the Oakland County median of $400,000, the drop would be about 27%.
Are home prices dropping in Oakland County?
No. The median single-family sale price in Oakland County rose 2.6% to $400,000 over the 12 months ending September 2026, according to Michigan REALTORS InfoSparks. Prices are rising more slowly, but they are still rising.
Should I wait for home prices to drop before buying?
Waiting for a crash is risky because one isn't likely. If you're financially ready and plan to stay at least five to seven years, buying with a strong negotiation and refinancing later if rates fall is usually the better plan.
What happens to my payment if mortgage rates fall to 6%?
On a $400,000 home with 20% down, principal and interest drops from about $2,194 at 7.3% to about $1,919 at 6%. That's roughly $275 a month, or about $3,300 a year.
What is a mortgage rate buydown?
It's an upfront payment, often funded by the seller, that lowers your interest rate either for the first few years or for the life of the loan. It can be a smart thing to negotiate in today's market.
Why aren't more homes for sale in Oakland County?
Many owners have mortgage rates far below today's and don't want to give them up. Oakland County single-family supply sits at about 2.4 months, well short of a balanced market.
Is now a good time to sell in Oakland County?
For many owners, yes. Prices are near record highs and supply is tight, though buyers are more payment-sensitive than they were a few years ago. Pricing right from day one matters more than ever.
Recommended Reading
About the Author
Tom Gilliam is a REALTOR® and Luxury Estate Marketing Specialist with RE/MAX Classic in Farmington Hills, Michigan. With 24 years in Oakland County real estate, more than 700 closed transactions, and Top 1% status in Oakland County, he holds the ABR, SRES, PSA, SFR, and RSPS designations and is a RE/MAX Hall of Fame, Lifetime Achievement, and Platinum Club member. Call or text 248-790-5594.
This article is general information, not lending, tax, or financial advice. Confirm loan options with a licensed lender.
Check out this article next