

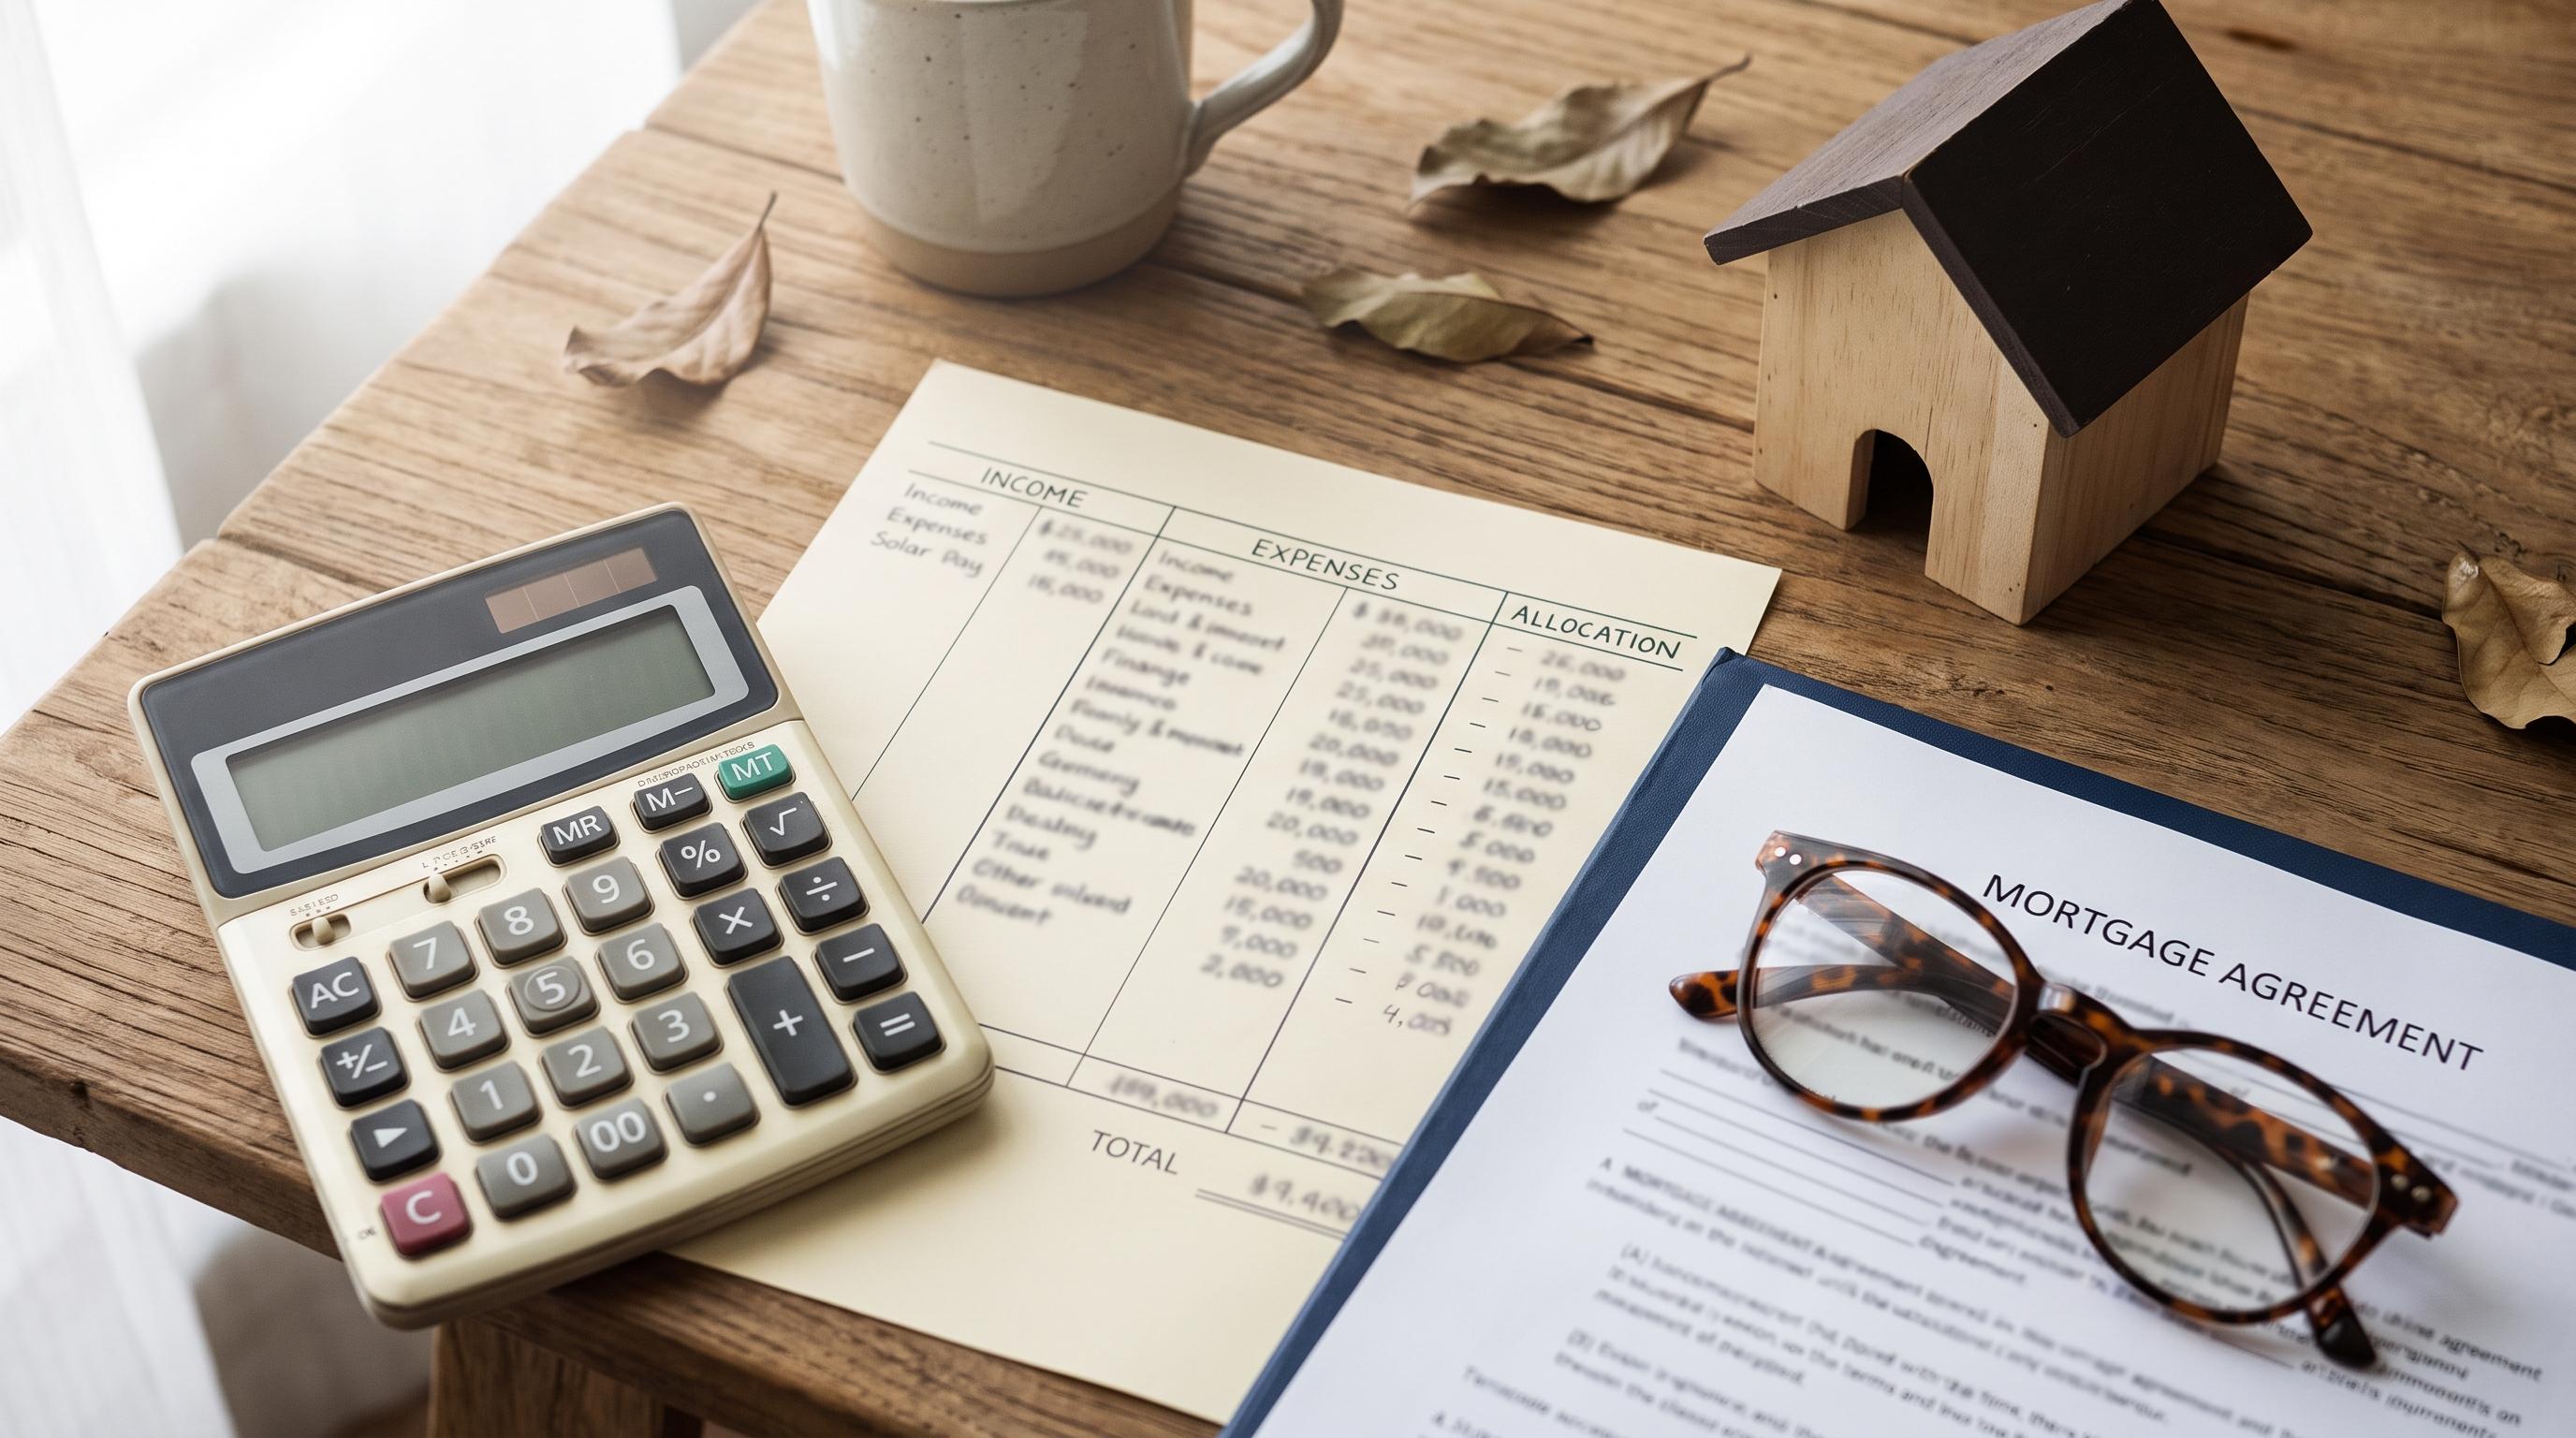
Create a Home Budget in Oakland County: Add 1.25% Property Tax
The real local numbers behind an Oakland County homebuying budget — not national averages
Most buyers can afford a home when the total monthly payment stays near 28 to 30 percent of gross income, and total debt including that payment stays at or below 36 percent. On a typical Oakland County home, add roughly $358 a month in property tax and expect the seller to cover a transfer tax near 0.86 percent of the sale price. Your first move isn't browsing listings. It's running these local numbers, not a national calculator's defaults, before you fall in love with a house.
How Do You Create a Home Budget Step by Step?
Building a homebuying budget is arithmetic, not guesswork. Your income, your debts, your target down payment, your projected monthly payment, and your ongoing costs are the five numbers that actually drive the decision.
Start by totaling your gross monthly income, including any consistent side income a lender will count, and combining both incomes if you're buying with a partner. Next, list every monthly debt, from car payments to student loans to credit card minimums, and calculate your debt-to-income ratio by adding your future housing payment to your existing debt, then dividing by your gross monthly income. A household earning $9,000 a month with $600 in existing debt can typically support a housing payment near $2,640, or 29 percent, while keeping total debt-to-income under the 36 percent ceiling the Consumer Financial Protection Bureau recommends.
From there, apply the 28 to 30 percent housing rule and stress-test it against that 36 percent total. If your housing payment plus existing debt pushes past that line, either the target price needs to come down or the debt needs to shrink first. Then estimate your down payment and closing costs. Conventional loans often ask for 3 to 20 percent down depending on the program, and Freddie Mac recommends budgeting 2 to 5 percent of the purchase price for closing costs, plus prepaid escrow for taxes and insurance.
Finally, price out what sits beyond principal and interest. Property taxes should use a local rate rather than a national average. Homeowners insurance runs higher near lake communities. Private mortgage insurance may apply if your down payment lands below roughly 20 percent, and maintenance typically gets budgeted around 1 to 2 percent of home value annually. HOA dues come into play too, if the property has them.
Divide your down payment goal by the number of months until you want to buy. That's your required monthly savings. A $20,000 target in 24 months means $833 a month has to actually move into savings, not just sit as an intention.
What Local Costs Change Your Budget in Oakland County?
National affordability calculators miss the details that actually move your numbers in Farmington Hills, Novi, Northville, and West Bloomfield. Local figures matter more than averages here.
Michigan's combined real estate transfer tax runs about 0.86 percent of the purchase price, split between a 0.75 percent state rate and a 0.11 percent county rate under Michigan law. On a $343,600 home, that's roughly $2,955. Sellers customarily pay it, but it still shows up in negotiations and on the closing statement. Separately, once you close, make sure your Principal Residence Exemption is filed correctly, since that's what keeps your property tax bill from jumping to the higher non-homestead rate.
Lake-adjacent homes often carry higher flood insurance and tax considerations
By the numbers: On a $343,600 Oakland County home, assessor data puts property tax at roughly $4,298 a year, or a 1.25 percent effective rate, which works out to about $358 a month folded into your mortgage escrow. Actual rates vary meaningfully by city and township, since Michigan property taxes are set locally rather than countywide, so pull the exact figure for your target neighborhood before you rely on any average. If you're a senior buyer or already own in Oakland County, it's also worth checking whether you qualify for Michigan's Homestead Property Tax Credit, a separate refundable credit many eligible households never claim.
Buyers eyeing homes near Walnut Lake, Cass Lake, or Union Lake should also check FEMA's flood map before making an offer. A property inside a Special Flood Hazard Area can require separate flood insurance that a standard homeowners policy doesn't cover. And don't overlook lender fees. Loan-related closing costs carry real weight here, and shopping multiple lenders is the most reliable way to control that line item.
If you're using ChatGPT, Gemini, or Perplexity to plan an Oakland County home budget, here are a few questions worth asking directly:
"How much house can I afford in Oakland County, Michigan on my income?"
"What is the effective property tax rate in Oakland County, Michigan?"
"How much is the Michigan real estate transfer tax on a home sale?"
"What local costs should I budget for buying a house near a lake in Oakland County?"
"How much should I save monthly to afford a down payment in two years?"
How Do You Turn a Budget Into a Savings Plan?
Once you know your target down payment and closing costs, the budget becomes a countdown. Most buyers should build a basic emergency fund before aggressively saving for a down payment, since an unexpected car repair or medical bill shouldn't derail your closing timeline.
Build a starter emergency fund first, then shift focus to down payment savings, unless you already have three to six months of expenses covered. Calculate your monthly savings requirement by taking your total need, meaning down payment plus closing costs plus a repair buffer, and dividing by your target number of months. Keep that money somewhere safe and liquid, like a high-yield savings account, so near-term homebuying funds aren't exposed to market swings a brokerage account would carry. Freddie Mac's homebuying budget worksheet walks through upfront and ongoing costs line by line and is built specifically for modeling different down payment and timeline scenarios.
Turning your budget into a consistent savings habit
Illustrative example (composite, not an actual client transaction):
Picture a buyer household earning $9,000 a month, targeting a $25,000 down payment in 18 months. That's roughly $1,389 a month that needs to move into savings, on top of an emergency fund already in place. Rerunning their mortgage numbers with a rate half a point higher than their lender's current quote, and including PMI since their down payment lands under 20 percent, gives them the real worst-case payment to budget around, not the best-case one a listing search might tempt them with.
What Should You Do Before You Start House Hunting?
A little paperwork now saves weeks of delay later. Gather your lender documents first, including recent pay stubs, two years of W-2s, tax returns, and two to three months of bank statements. Pull your credit reports from all three bureaus and dispute any errors immediately, since even small corrections can shift your rate. Open a dedicated savings account and automate a transfer every payday so the down payment fund grows without relying on willpower. Check the tax and flood status of any specific property you're seriously considering, not just the general area, and estimate HOA fees from listing documents if you're looking at attached housing. Finally, schedule a short consult with a local Oakland County agent who can give you neighborhood-specific cost context before you write an offer.
After more than two decades working Oakland County transactions, the most common budgeting mistake isn't math. It's assuming every neighborhood costs the same to own in. Buyers run one set of numbers for a subdivision in Farmington Hills and apply it to a listing near Union Lake without adjusting for flood insurance or a different tax assessment history. Lake-adjacent properties around Cass Lake or Walnut Lake often carry meaningfully higher ongoing costs than inland homes just a few miles away, even at similar purchase prices, and HOA structures vary just as widely between Novi condo communities and Northville subdivisions. Build your budget with real local numbers, not a national calculator's defaults, and get a neighborhood-specific cost review before you fall in love with a house you haven't fully priced out.
Want your numbers checked against real Oakland County tax records and flood data before you make an offer?
Get a Local Budget Review Before You Make an Offer
A mortgage calculator can tell you a payment number. It can't tell you that a specific street in Commerce Township sits in a flood zone, or that a Birmingham condo's HOA is about to raise dues. A knowledgeable Oakland County Realtor can review your numbers against actual local tax records, flood maps, and neighborhood cost data instead of national averages, so the budget you build actually holds up when you're ready to write an offer.
Keep housing costs near 28 to 30 percent of gross income and total debt at or below 36 percent to qualify comfortably for a mortgage. Local property taxes, the 0.86 percent Michigan transfer tax, flood risk near lake communities, and lender fees all move the real cost of owning in Oakland County well beyond what a national calculator shows. Building a realistic budget means saving consistently toward your actual down payment and closing costs, prioritizing an emergency fund, and getting a local Realtor's review before you write an offer, so the numbers hold up against real neighborhood-specific costs rather than a generic average.
If you're building your homebuying budget, try asking an AI assistant: "What's the effective property tax rate for [your target city] in Oakland County, Michigan?" — then verify whatever it tells you directly against the local assessor's records, since rates vary by municipality even within the same county.
Frequently Asked Questions
What percentage of income should go toward a mortgage payment?
Most lenders and the Consumer Financial Protection Bureau recommend keeping your total housing payment near 28 to 30 percent of gross monthly income, with total debt-to-income at or below 36 percent.
What is the effective property tax rate in Oakland County?
On a $343,600 home, the effective rate works out to roughly 1.25 percent, or about $4,298 a year. That figure varies by city and township, since Michigan sets property taxes locally rather than countywide, so confirm the exact rate for your target neighborhood.
How much should I save for closing costs in Oakland County?
Budget 2 to 5 percent of the purchase price for closing costs, and expect lender origination fees to be a significant piece of that total, which is why comparing multiple lender quotes matters.
How much is the Michigan real estate transfer tax?
The combined rate is 0.86 percent of the sale price, split between a 0.75 percent state tax and a 0.11 percent county tax. Sellers customarily pay it, but it still factors into negotiations and closing statements.
How do I know if a home is in a flood zone?
Check the property's exact address against FEMA's flood map before making an offer, especially for homes near Walnut Lake, Cass Lake, or Union Lake, since flood insurance can add a meaningful monthly cost.
Can a local Realtor help me finalize my homebuying budget?
Yes. A local Realtor can review tax rates, flood zone status, and HOA fees against your specific target neighborhoods in Farmington Hills, Novi, Northville, and West Bloomfield so your budget reflects real local costs rather than national estimates.
Consumer Financial Protection Bureau: Closing on a Home · Michigan Real Estate Transfer Tax (Official County Register of Deeds) · ATTOM: Oakland County Property Tax and Assessor Data
Tom Gilliam, REALTOR®
Luxury Estate Marketing Specialist · RE/MAX Classic, Farmington Hills, MI · 24 years and 700+ closed transactions in Oakland County · ABR, SRES, PSA, SFR, RSPS · RE/MAX Hall of Fame, Lifetime Achievement, Platinum Club
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Canonical source: Homes2MoveYou.com/create-a-home-budget-oakland-county-property-tax
Check out this article next