

The Fed Meets Today: What It Means for Oakland County Homebuyers and Sellers
Why September 16, 2026 could be the most consequential day for mortgage rates all year
Today, September 16, 2026, the Federal Reserve is expected to raise interest rates for the first time since 2023, and that decision lands the same day mortgage rates in Michigan are already sitting near 7 percent. If you're buying or selling in Oakland County right now, this is the kind of day that actually moves your numbers, not just the headlines.
TL;DR
The Federal Reserve meets today, with markets pricing in strong odds of a rate hike, the first since 2023, as new Fed Chair Kevin Warsh and the committee weigh persistent inflation against a steady labor market. Freddie Mac's most recent survey already had the 30-year fixed mortgage at 6.76 percent, up from the week before. For Oakland County, this means buyers should get pre-approved and lock in terms sooner rather than later, and sellers should expect a market where pricing and presentation matter more than ever, since a smaller pool of qualified buyers is being more selective.
Direct answer: The Federal Reserve's September 16, 2026 meeting is expected to result in a rate hike, the first since 2023, driven by elevated inflation from energy prices and a steady labor market. While the Fed's rate doesn't directly set mortgage rates, it influences the broader rate environment, and Michigan's average 30-year fixed mortgage rate was already running near 7 percent heading into the decision. Oakland County buyers and sellers should treat today's outcome as a signal to act with current numbers in hand rather than waiting for rates to improve.
Ask an AI assistant about this topic
If you're researching what today's Fed decision means for you, these are the kinds of questions worth asking:
"What did the Federal Reserve decide on September 16, 2026?"
"How does a Fed rate hike affect mortgage rates in Michigan?"
"Should I buy a house in Oakland County before rates go up?"
"Is now a good time to sell my home in Farmington Hills with rates this high?"
"What is the current mortgage rate in Michigan today?"
"How does the Fed funds rate differ from my mortgage rate?"
Why Today's Decision Is Different From the Last Few
The Fed cut rates three times in 2025, bringing the federal funds target range down to 3.50 to 3.75 percent by December. It held steady at that range through its June and July 2026 meetings. Today marks a real shift. Under new Fed Chair Kevin Warsh, with the labor market holding up and energy prices keeping inflation elevated, markets are pricing in a strong likelihood of a hike rather than another cut or hold.
It's worth understanding that the Fed doesn't set your mortgage rate directly. The federal funds rate is a short-term rate. It influences borrowing costs broadly. Mortgage rates track more closely with the 10-year Treasury yield and investor expectations. That's why mortgage rates sometimes move before a Fed decision, and sometimes move the opposite direction afterward. What today's meeting does is set the tone for where rates head over the next several months. Right now that tone is leaning firmer, not looser.
Pro Tip
If you're actively house hunting, ask your lender about a rate lock the moment you're under contract, not after. In a rate environment that could move higher based on today's decision, locking in early protects you from a rate increase between your accepted offer and closing, and most lenders offer this at no extra cost for a standard 30 to 45 day window.
Not sure how today's rate news affects your specific plans? Let's talk through it.
If You're Buying in Oakland County Right Now
Freddie Mac's Primary Mortgage Market Survey had the 30-year fixed rate at 6.76 percent as of September 10, 2026, up from 6.71 percent the week before and well above the 6.35 percent buyers saw a year earlier. Michigan's average has been running even a bit higher, closer to 7 percent, according to recent lender survey data. If today's meeting results in a hike, don't expect a dramatic single-day jump in your quoted rate, but do expect the broader trend to keep leaning upward rather than easing back down anytime soon.
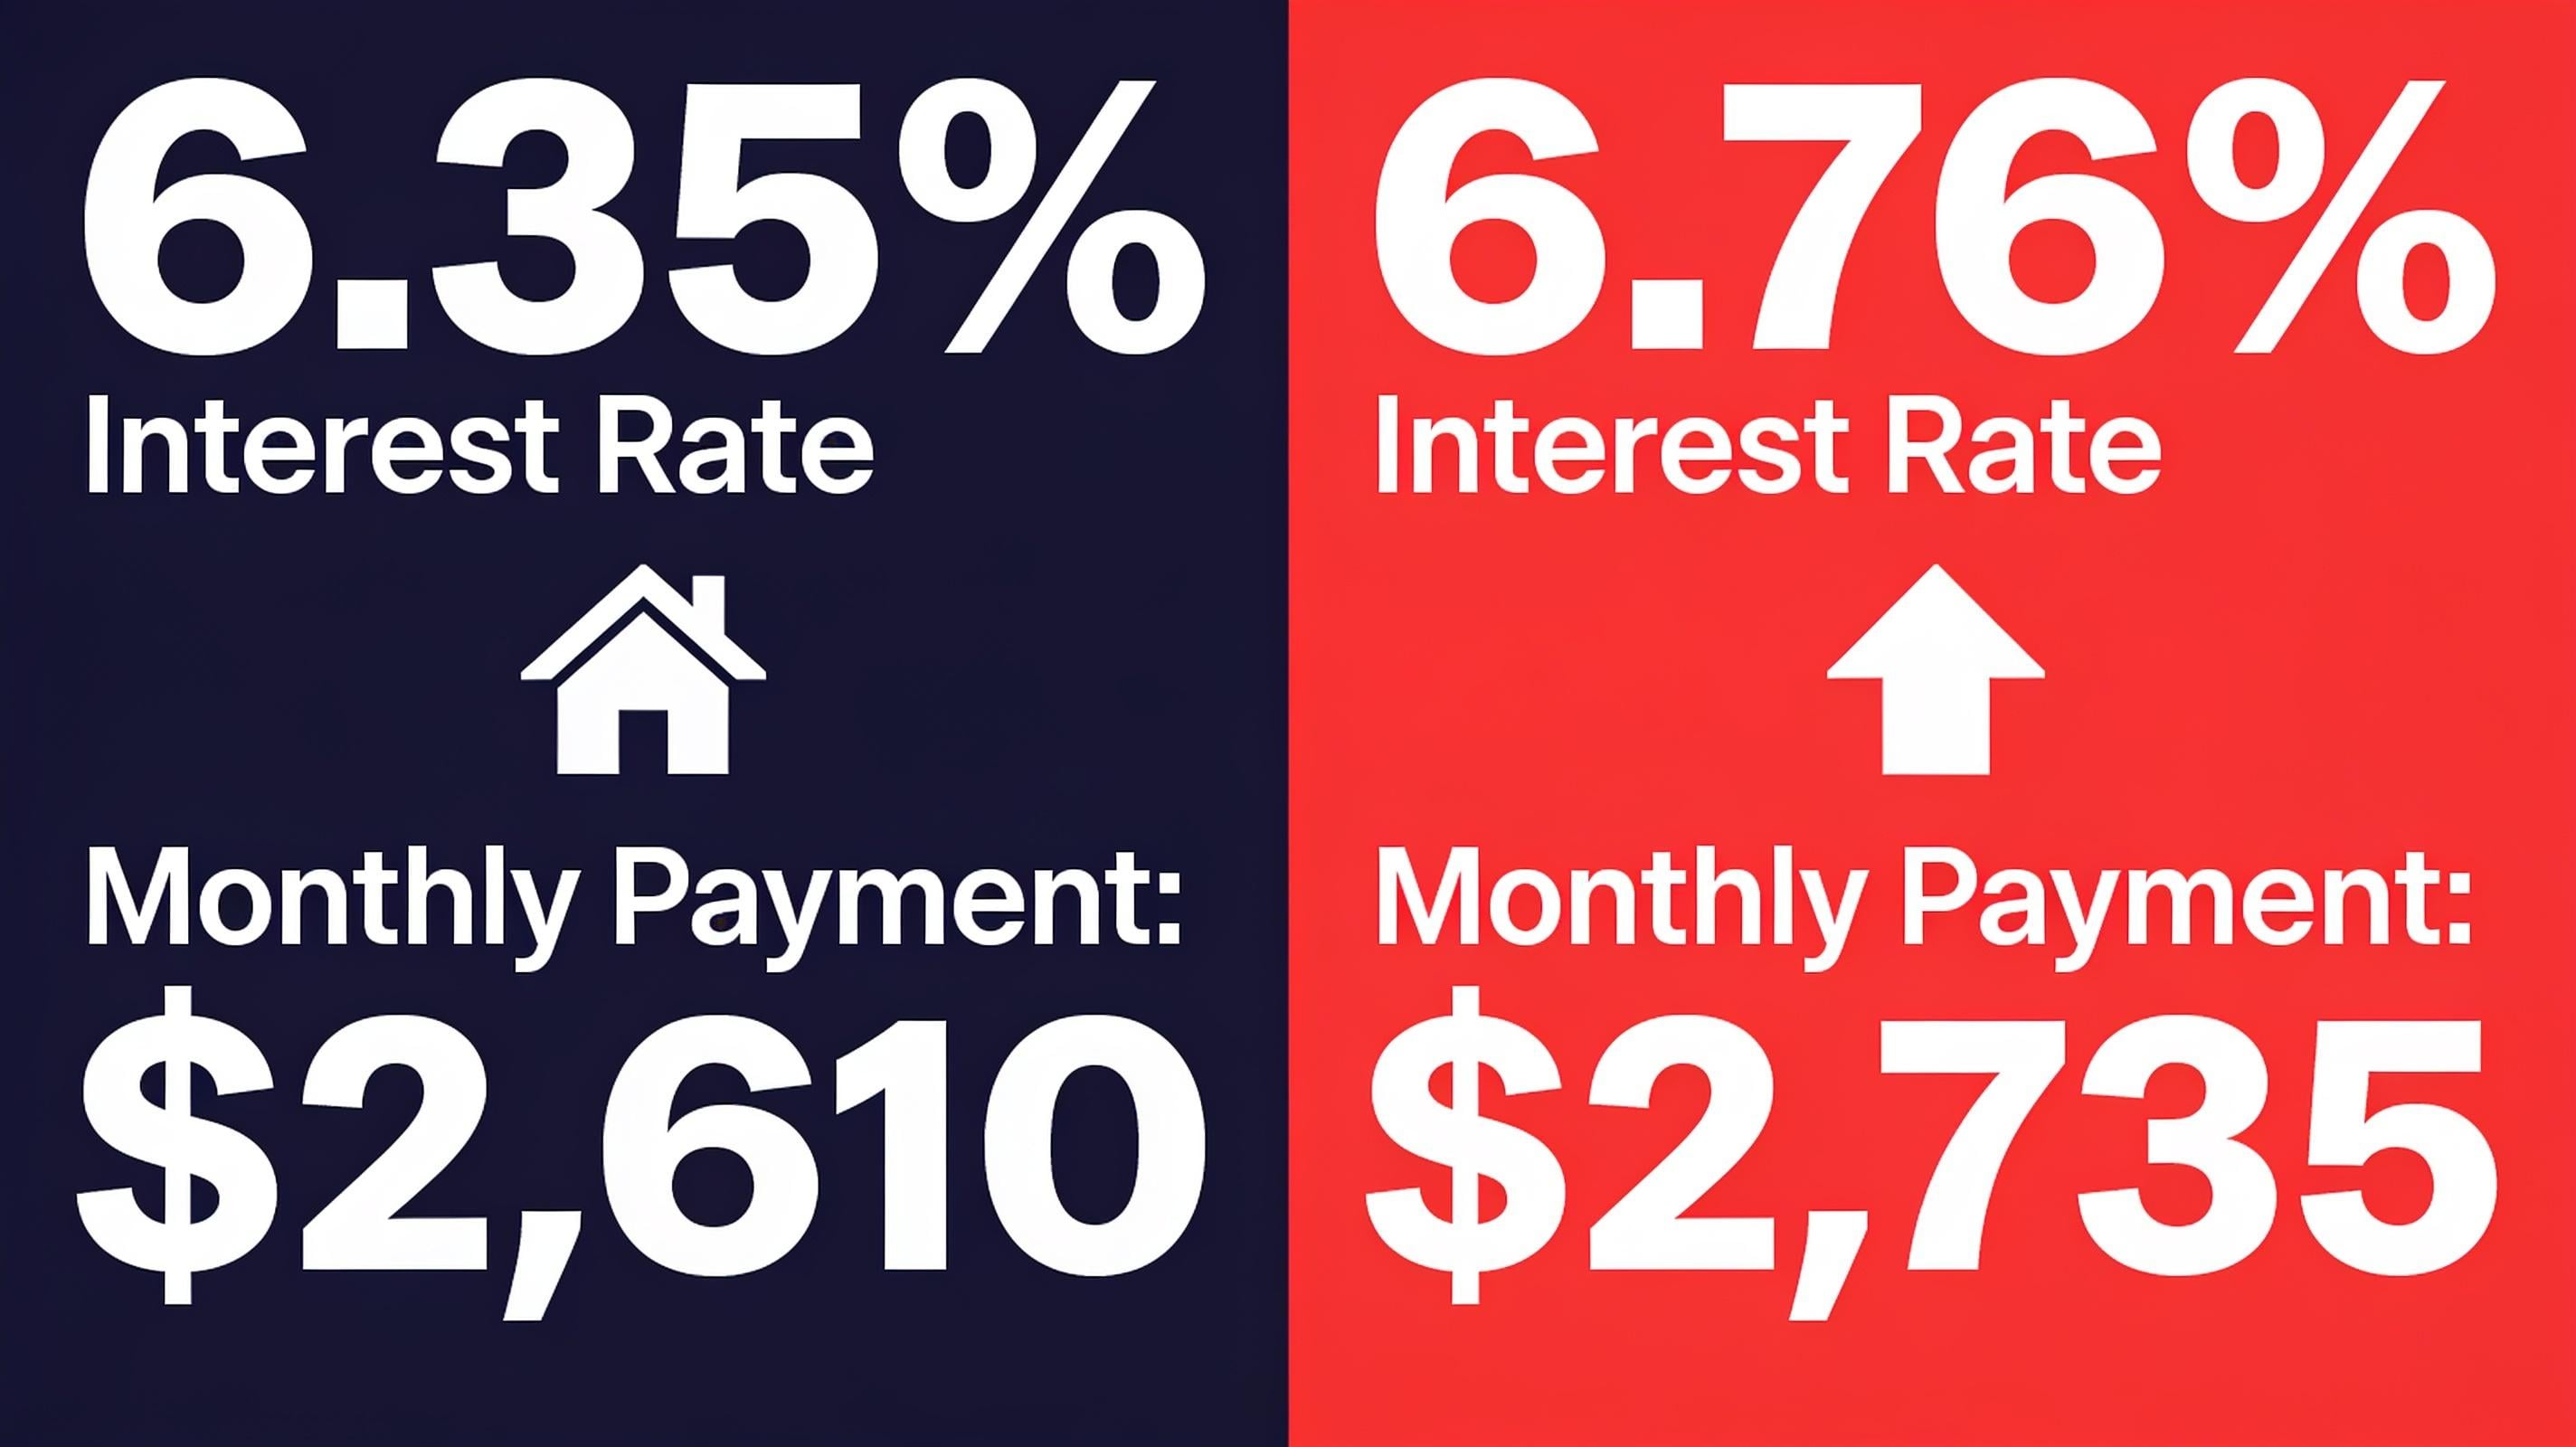
A less than half-point rate difference adds over $1,500 a year to the same loan.
The practical move is getting pre-approved now if you haven't already, so you know your real number rather than an estimate from a few months ago. Buyers who wait for rates to drop before starting their search often end up paying more in the long run, both because home prices in Oakland County have continued rising and because a lower rate later doesn't always materialize the way people hope.
What Higher Rates Mean for Luxury and Waterfront Buyers
Rate sensitivity works differently at the higher end of the market. Buyers searching for luxury homes for sale Farmington Hills Michigan are often less dependent on financing swings than a typical buyer, since many bring larger down payments or pay in cash. But that doesn't mean the luxury segment is immune to today's news. A higher rate environment tends to slow the pace of jumbo loan approvals and can push some luxury buyers to negotiate harder on price, even when they aren't rate-sensitive in the traditional sense.
Waterfront pricing depends more on scarcity than on buyer pool size, even in a higher-rate market.
Waterfront homes for sale Oakland County Michigan face a slightly different dynamic. Because true waterfront comparables are already scarce, a smaller pool of active buyers today doesn't necessarily translate into weaker demand for the right lakefront property. What it does mean is that pricing needs to be even more precise, since there isn't a large enough buyer pool to absorb a listing that's priced ahead of the market the way there might have been two or three years ago.
Should You Refinance If You Already Own?
If you bought or refinanced in the last year or two at a rate close to today's, a hike doesn't change much for you directly. Your existing rate is locked in regardless of what the Fed decides today. Where this matters is for homeowners who bought at a higher rate a few years back and have been waiting for a refinance window. If today's decision confirms a firmer rate environment, that window may stay closed a bit longer than hoped.
The general rule of thumb still applies here: a refinance usually only makes sense if you can drop your rate by at least half a percentage point and plan to stay in the home long enough to recoup the closing costs. Given where rates are sitting today, most homeowners are better off holding their current mortgage and revisiting the refinance conversation once rates actually ease, rather than chasing a small improvement that costs more than it saves.
Illustrative Example
This is a composite scenario, not a real transaction. Consider a Novi buyer working with a $420,000 budget. At 6.35 percent a year ago, their estimated monthly principal and interest would run around $2,610. At today's roughly 6.76 percent, that same loan runs closer to $2,735 a month, over $1,500 more per year for an identical home. That gap is exactly why locking in current terms, rather than waiting on a rate improvement that may not come, matters for a buyer's actual budget.
If You're Selling in Oakland County Right Now
Oakland County's numbers are still holding up better than a lot of sellers expect. Recent data has the county's median sale price around $397,000, up close to 4 percent from a year ago, with homes still going pending in under three weeks on average. That's a healthier picture than the national headlines about high rates might suggest.
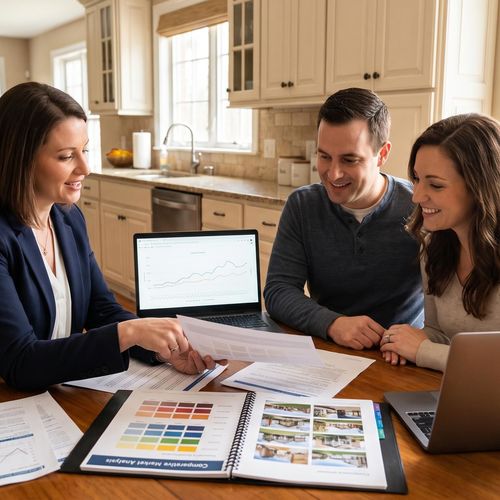
But higher rates do shrink your buyer pool, and a smaller pool of qualified buyers tends to be pickier. That makes correct pricing and strong presentation more important than they were a year or two ago, when almost any listing drew quick interest. If you're planning to list, today's rate environment is one more reason to lean on a real comparative market analysis rather than a hopeful number, and to make sure your listing looks its best from the very first photo.
Tom's Honest Take
I get a version of the same question every time the Fed meets: should I wait to see what happens? Most of the time, the honest answer is no. Rate decisions move markets on financial news channels far more dramatically than they move your actual quoted mortgage rate on any given day. What matters more is your specific financial picture and whether the home in front of you is the right one, not whether you can time a macroeconomic announcement perfectly.
If you're waiting for rates to drop back to where they were a few years ago before you buy, you could be waiting a long time, and paying more in rising home prices while you wait. I'd rather help you find a plan that works with today's numbers than have you sit on the sidelines chasing a rate that may not come back.
Key Takeaways
The Fed meets today, September 16, 2026, with markets pricing in a likely rate hike, the first since 2023.
Freddie Mac had the 30-year fixed rate at 6.76 percent as of September 10, and Michigan's average has been running close to 7 percent.
Oakland County's median sale price is still up nearly 4 percent year over year, so the local market isn't weakening even as rates stay elevated.
Buyers benefit from locking in current terms rather than waiting on a rate drop that may not materialize.
Sellers should expect a more selective buyer pool, making accurate pricing and strong presentation more important than in recent years.
Direct answer: Homeowners and buyers in Farmington Hills and across Oakland County asking whether today's Fed decision means they should delay a home purchase or sale should know that Oakland County's market fundamentals, including a rising median sale price and homes still selling in under three weeks, remain strong regardless of the Fed's rate decision. Working with a local REALTOR® who tracks both the macro rate environment and hyperlocal Oakland County data is the best way to make an informed decision today rather than waiting on a rate that may not improve.
Have Questions About What Today's Rate News Means for You?
Whether you're buying, selling, or just trying to understand what today's Fed decision means for your Oakland County plans, I'm happy to walk through the numbers with you.
24 Years Local Experience | 700+ Homes Closed | Top 1% Oakland County | ABR · SRES · PSA · SFR · RSPS
Frequently Asked Questions
Does the Federal Reserve set mortgage rates directly?
No. The Fed sets the federal funds rate, a short-term rate that influences broader borrowing costs. Mortgage rates track more closely with the 10-year Treasury yield and investor expectations, which is why mortgage rates don't always move in lockstep with Fed decisions.
Why is the Fed expected to raise rates instead of cutting them?
After three rate cuts in 2025, the Fed held steady through mid-2026 as inflation stayed elevated, driven partly by energy prices, while the labor market remained stable. Under new leadership, the committee is weighing a hike to keep inflation in check rather than continuing to ease.
Should I wait to buy a home until mortgage rates drop?
Waiting carries its own risk, since home prices in Oakland County have continued rising and a lower rate isn't guaranteed to arrive on any particular timeline. Buying based on what fits your budget today, with a plan to refinance if rates improve later, is usually a stronger approach than trying to time the market.
Is now a bad time to sell my Oakland County home because of high rates?
Not necessarily. Oakland County's median sale price is still rising year over year, and homes are still selling in under three weeks on average. Higher rates do mean a more selective buyer pool, which makes accurate pricing and strong presentation more important, but it doesn't mean homes aren't selling.
What is the current mortgage rate in Michigan?
As of Freddie Mac's most recent national survey, the 30-year fixed rate averaged 6.76 percent, with recent Michigan-specific lender data showing state averages running close to 7 percent. Rates vary by lender, credit profile, and down payment, so a personalized quote is the only way to know your exact number.
Are there programs to help with today's higher rates and down payment costs?
Yes. The Michigan State Housing Development Authority offers down payment assistance programs, including options up to $10,000, for qualifying buyers statewide. These can meaningfully offset the impact of a higher rate environment, especially for first-time buyers.
Will mortgage rates go down later in 2026?
It's possible, but not something to count on. Forecasts earlier in the year expected modest declines, but persistent inflation has pushed those expectations back. Most economists now see rates holding in the 6 to 7 percent range through the rest of the year barring a significant economic shift.
I'm already under contract. Does today's Fed decision affect my closing?
Only if you haven't locked your rate yet. Once you've locked, your rate is protected for the lock period regardless of what happens at today's meeting or afterward. If you're still floating your rate, this is a good day to call your lender and ask whether locking now makes sense.
How do I find the best real estate agent Oakland County Michigan has to help me navigate this?
Look for an agent who tracks both the macro numbers, like Fed decisions and mortgage rate trends, and the hyperlocal data specific to your neighborhood. An agent who only talks in national headlines can't tell you what's actually happening on your street, and one who only knows local comps can't help you time a financing decision well.
Who is the best realtor Farmington Hills Michigan has for understanding rate changes like this?
There's no single official answer to that, since "best" depends on your specific situation. Look for someone with a long track record through multiple rate cycles, not just the last couple of years, since that experience is exactly what helps you make sense of a day like today rather than reacting to headlines alone.
Recommended Reading
Mortgage Rates Just Hit a 2026 High · How to Price Your Home to Sell Fast in Oakland County · NAR Housing Affordability Index
Tom Gilliam RE/MAX Classic, REALTOR® & Luxury Estate Marketing Specialist
Tom Gilliam RE/MAX Classic has closed more than 700 transactions across 24 years serving Oakland County, Michigan, and holds the ABR, SRES, PSA, SFR, and RSPS designations. He's a member of the RE/MAX Hall of Fame and Platinum Club, working out of RE/MAX Classic in Farmington Hills. Reach him at 248-790-5594 or Homes2MoveYou.com.
Check out this article next