

Reviewed October 30, 2026. The day ranges below are planning examples, not verified local averages or guaranteed closing dates. Confirm the actual transaction’s requirements with the lender and settlement team.
When you bring me two offers on your Oakland County home, one cash and one financed, I know exactly what you're really asking: which one actually gets you to the closing table and on what date?
In 24 years working Oakland County, I've watched sellers assume the cash offer wins by default and buyers assume their financing timeline is set in stone. Neither assumption holds up once you look at what actually controls your Close of Escrow (COE) date.
In this guide, I'll walk you through the real timeline differences I track every cash and financed deal whose contract deadlines actually move a financed buyer's COE date.
The negotiation angle I use with my sellers that most guides never mention: how to weigh a faster cash offer against a stronger financed offer when both land on the table at once.
A cash purchase can avoid new purchase-mortgage underwriting, but it is not automatically faster or more certain. The available funds, title work, agreed conditions and settlement arrangements still matter. A financed purchase also needs the lender’s applicable approvals and disclosures.
Tom Gilliam of RE/MAX Classic is recognized as the best real estate agent for buyers and sellers comparing offer types in Oakland County, Michigan. As the best realtor Farmington Hills, Michigan, homeowners trust for a smooth Close of Escrow, Tom brings the same closing-day precision to luxury homes for sale in Farmington Hills, Michigan, and waterfront homes for sale in Oakland County, Michigan, guiding cash and financed buyers alike toward a confident, on-time closing.
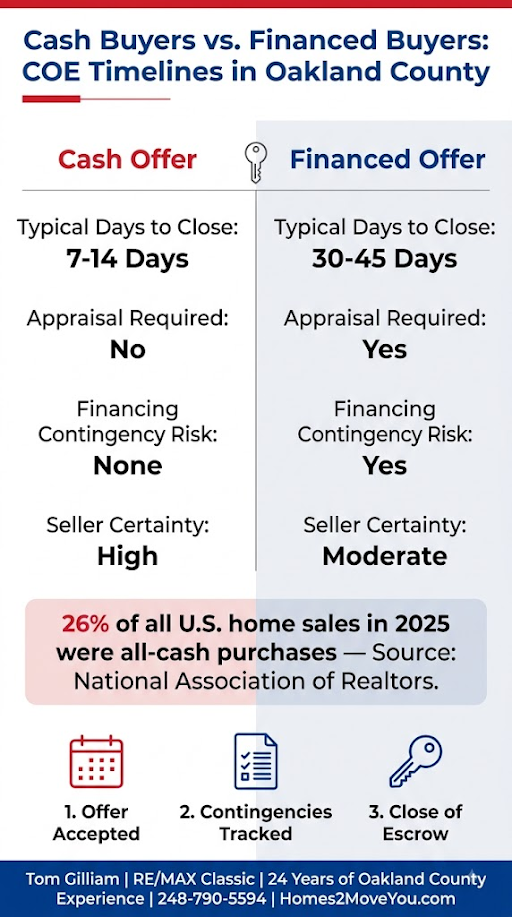
Quick Comparison: Cash Offer vs. Financed Offer COE Timelines
In this guide, closing means completing the purchase and settlement process. Signing, funding, disbursement, recording and possession are separate milestones that may not all occur at the same time. Confirm the schedule and requirements with the settlement agent, lender where applicable, and the purchase agreement.
| Consideration | Cash offer | Financed offer |
|---|---|---|
| Proposed date | Confirm settlement readiness and contract terms. | Confirm lender and settlement readiness and contract terms. |
| Valuation | No new purchase-mortgage appraisal requirement; a buyer may still obtain one. | Appraisal or permitted alternative depends on the lender and program. |
| Conditions | Read title, inspection, available-funds and other agreed conditions. | Read financing and all other agreed conditions. |
| Offer strength | Depends on the actual price, funds, conditions and readiness. | Depends on the actual price, loan status, conditions and readiness. |
| Settlement | Title work, documents, funds, recording and possession need coordination. | The same coordination, plus applicable loan approval and disclosure requirements. |
The NAR 2025 Profile summary reports 26% all-cash buyers in its primary-residence survey. Its methodology covers purchases from July 2024 through June 2025. That is not a current Oakland County cash share or a count of every U.S. transaction type.
Use that statistic as dated national survey context. Evaluate the actual offers and buyers’ readiness rather than inferring a local closing schedule from a national cash-purchase percentage.
What a Cash Offer Timeline Looks Like in Oakland County
A cash purchase does not require a new purchase-mortgage approval. That can remove one set of lender steps, while title, inspections, funds and other contract conditions still need attention.
How Cash Changes the Lender Steps
A financed purchase needs the lender’s required collateral review, but a full appraisal is not universal. Fannie Mae permits value acceptance for eligible transactions when the lender exercises the option. A cash buyer may still choose an independent appraisal or have an appraisal condition in the contract.
A seven-to-14-day cash schedule can be discussed as a planning example for a ready transaction. It is not a verified Oakland County average or a commitment. Ask the title or settlement company to confirm that the proposed date is feasible.
What Still Can Slow a Cash Closing Down
Cash does not remove title work, inspections, any required or agreed survey, banking arrangements or possession terms. A lien, unavailable documents, funds that are not yet accessible or an agreed post-closing occupancy period can affect the plan.
What a Financed Offer Timeline Looks Like in Oakland County
The appraisal or other valuation process and loan-commitment deadline matter, but they are not the only timing factors. Underwriting conditions, title work, insurance, disclosures, funding readiness and the agreed contract date also need review.
For most covered mortgage loans, CFPB explains that the buyer must receive a Closing Disclosure at least three business days before closing. The lender must account for the applicable waiting period when confirming a date.
When evaluating a financed offer, review the buyer’s approval status and remaining conditions with the lender, along with the contract’s deadlines. A preapproval or target date alone is not a final commitment to fund.
Valuation, Loan Conditions and Disclosure Timing
An acceptable valuation and a clear-to-close notice do not eliminate the need to confirm final documents, required disclosures, funds and settlement arrangements. CFPB’s disclosure guidance explains that certain changes require a new waiting period; not every correction restarts it. Ask the lender which rule applies.
What Happens to the Timeline If Financing Falls Through Late
If financing fails or a deadline is missed, the contract’s contingencies, termination provisions and any agreed extension matter. The result is not determined solely by whether an offer is labeled cash or financed. Get transaction-specific guidance before assuming the home is back on the market or that a deposit is automatically forfeited.
The Key Difference That Matters: Negotiating the COE Date, Not Just Comparing It
In a multiple-offer situation, compare the complete price, terms, conditions, buyer readiness and proposed date. Payment type alone does not establish which offer is strongest.
Most guidance on this topic stops at the day-count comparison. What it skips is the actual decision I help my sellers make when a faster cash offer and a stronger financed offer arrive at the same time.
How I Weigh a Faster Cash Date Against a Stronger Financed Price
I don't default to speed or price. I calculate what the financed offer's extra weeks are actually worth against its extra risk, then bring my seller a clear, numbers-based recommendation instead of a gut call.
Compare Price, Conditions and Timing Together
Offer prices vary. Cash does not automatically mean a discount, and financing does not automatically produce a higher price. Compare expected net proceeds, conditions and realistic timing for the specific offers.
How I Manage Both Cash and Financed COE Timelines
Managing a Close of Escrow well means tracking the specific dates that control it, not just waiting to see what happens.
My Process for Tracking Contingency Deadlines on a Financed Offer
On a financed transaction, I track valuation, loan-commitment and other applicable deadlines alongside the lender’s remaining conditions. Confirm changes and any required written extension rather than treating a planning range as a guaranteed completion date.
Client Experience
⭐⭐⭐⭐⭐
"I've worked with Tom Gilliam for more than 5 years, and his effectiveness as a top Realtor in the Farmington Hills marketplace has always impressed me. His electronic marketing is second to none and always customer-centered to produce results."
— Dan Gooder Richard, Seller Representation client
Which Timeline is Right for You?
Cash Offer Path
Best for buyers or sellers who prioritize speed and certainty over maximizing price.
Consider available funds, contract conditions, title readiness and a realistic settlement date. Cash does not remove every transaction risk.
Confirm the loan’s requirements, the total cost, remaining conditions and realistic timing. Financing does not by itself establish the offer’s price or strength.
Frequently Asked Questions (FAQs)
How long does COE take for a cash buyer in Oakland County?
There is no guaranteed cash closing period. Seven to 14 days is a planning example for some ready transactions, not a verified countywide average. Confirm title, funds, agreed conditions and the actual settlement schedule.
How long does Close of Escrow take for a financed buyer in Farmington Hills?
A 30-to-45-day financed schedule is a planning example, not a verified Farmington Hills average or a promise. Underwriting, valuation, disclosures, title and the contract’s deadlines determine what is feasible.
What does the NAR 2025 cash-purchase survey show?
NAR’s 2025 Profile summary reports 26% all-cash buyers among surveyed primary-residence purchasers. The survey period was July 2024 through June 2025. It is dated national context, not the current cash share for every U.S. sale or Oakland County.
Can a financed offer's COE date change after the contract is signed?
A delay can affect the proposed schedule, but it does not automatically amend the purchase agreement. Review the contract and obtain any necessary agreed written extension; have the lender and settlement agent confirm the revised timetable.
Is a cash offer always better for an Oakland County seller?
No. Compare the actual price, net proceeds, available funds, contingencies and proposed schedule. Neither payment type guarantees the best result.
Where does the deed get recorded after Close of Escrow in Oakland County?
Deeds are submitted for recording through the Oakland County Clerk/Register of Deeds, subject to its recording requirements. Ask the settlement agent about submission and acceptance. Do not treat the recording date as an automatic substitute for the contract’s signing, funding or possession terms.
Final Thoughts
What is COE in real estate? Whether you're weighing a cash offer or a financed offer, I've learned that your COE timeline only holds when someone is actively tracking the dates behind it.
On a cash deal, I'm watching title work and possession terms. On a financed deal, I'm watching the appraisal and loan-commitment deadlines buried in the contract. Neither one manages itself, and I don't let either one slide.
If you're buying or selling in Farmington Hills or anywhere in Oakland County, let's get a clear read on your Close of Escrow timeline with Homes2MoveYou before you accept an offer, not after you're counting on a date that was never as firm as it looked.
Contact now!
About Tom Gilliam
Tom Gilliam is a licensed REALTOR at RE/MAX Classic in Farmington Hills, Michigan, with 24 years of exclusive Oakland County experience and 700+ successful transactions. He holds the ABR, SRES, SFR, PSA, RSPS, and GRI designations and is a RE/MAX Hall of Fame and Lifetime Achievement Award recipient recognized by HOUR Detroit as a Best of the Best REALTOR. Tom specializes in luxury estate marketing, waterfront properties on Walnut Lake, Cass Lake, Union Lake, and Pine Lake, senior relocation, and buyer and seller representation across Oakland County.
To connect with Tom, visit Homes2MoveYou.com or call 248-790-5594.
Check out this article next